
Most motorbike loan pages show you one lender’s best promotional rate. That’s not the rate most people actually get. Here’s what motorbike loans really cost once your credit score and bike age are factored in, plus how to pick between secured and unsecured finance.
Quick Answer: Motorbike Loans
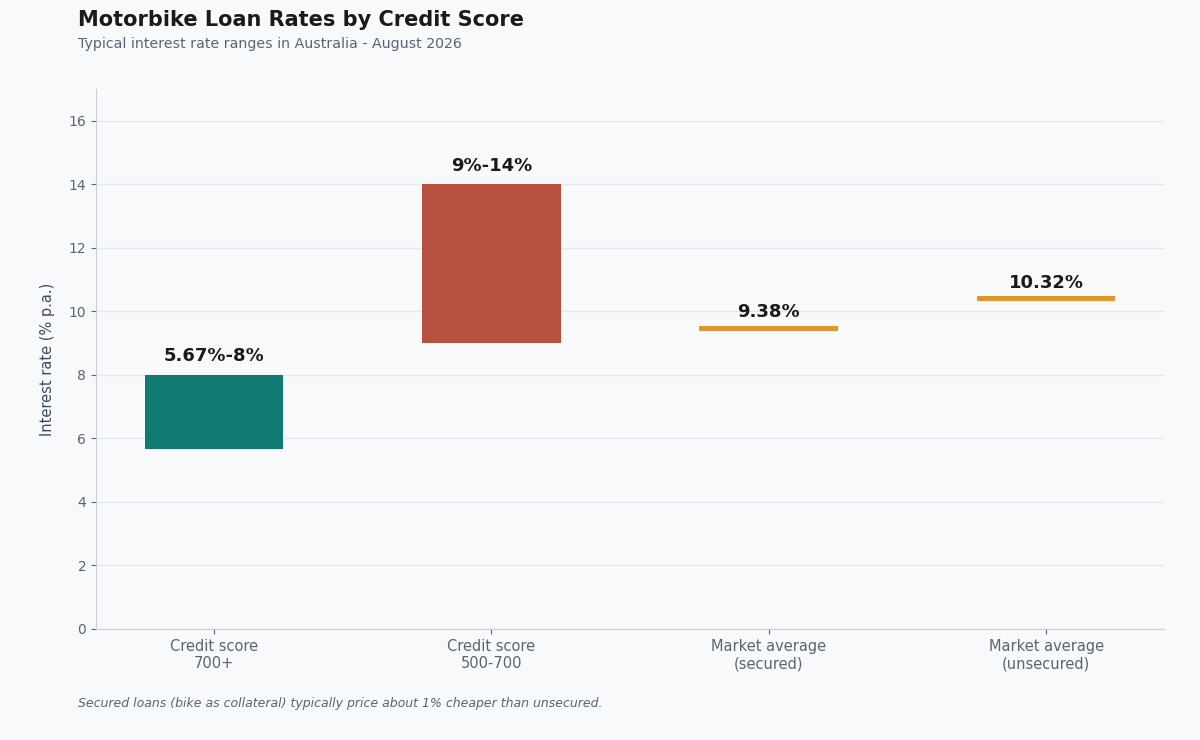
Motorbike loans in Australia average around 9.38% for secured loans and 10.32% for unsecured loans, though your actual rate depends heavily on your credit score. A score above 700 can get you rates from 5.67% to 8%. A score between 500 and 700 usually means 9% to 14% instead. Secured loans, where the bike itself backs the loan, run about 1% cheaper than unsecured ones. Bikes older than 7 years typically don’t qualify for secured financing at all. Dealer promotional finance can sometimes beat both, with rates as low as 4.99% to 7.99%.
Motorbike Loans: Why Your Rate Might Be Higher Than the Ads Show
- Advertised rates are usually the best-case scenario. Lenders lead with their lowest possible rate, which only goes to borrowers with strong credit and low-risk loans.
- The real market average tells a different story. Across Australia, secured personal loans average 9.38% and unsecured ones average 10.32%. That’s a more realistic starting point than any single lender’s headline rate.
- Your credit score is the single biggest factor. A score above 700 typically unlocks rates from 5.67% to 8%. Drop into the 500-700 range and expect 9% to 14% instead.
- The gap between these tiers is significant. So checking your credit score before you shop for a loan tells you which end of the pricing range you’re likely to land in.
Secured vs Unsecured: The Real Trade-Off
- A secured loan uses the bike itself as collateral. This typically means a lower rate, roughly 1% cheaper than an equivalent unsecured loan.
- The catch is real: the lender can repossess the bike if you default. That’s the trade you’re making for the lower rate, not a hidden fee or a technicality.
- Unsecured loans cost more but come with more flexibility. You can often borrow for gear, helmets, and accessories alongside the bike itself, not just the purchase price.
- Borrowing limits differ meaningfully between the two. Secured loans can stretch past $100,000 for the right buyer, while unsecured loans usually cap out between $5,000 and $60,000.
If Your Bike Is Older Than 7 Years
- Standard secured financing usually isn’t available for older bikes. Most lenders set an age cutoff around 7 years, after which the bike no longer qualifies as adequate collateral.
- Unsecured finance becomes the realistic option instead. You’ll likely pay a higher rate, but it remains available regardless of the bike’s age.
- Some specialist or dealer finance may still work. It’s worth asking directly, since policies vary more on this point than on almost anything else in bike lending.
- Buying privately versus through a dealer can also affect your options. Dealers sometimes have finance partnerships that are more flexible on older stock than a standalone lender would be.
Why a 4-5 Year Term Usually Prices Best
- Loan terms for motorbike finance typically range from 1 to 7 years. Within that range, 4 to 5 years tends to be treated as the pricing sweet spot by lenders.
- Shorter terms mean higher monthly repayments, which can strain approval. Lenders assess affordability, so a term that’s too short can actually work against you.
- Longer terms spread the cost but usually cost more in total interest. So there’s a real trade-off between monthly affordability and total cost over the life of the loan.
- Landing in the middle tends to balance both concerns. A 4-5 year term keeps repayments manageable while avoiding the interest blowout of stretching a loan too long.
Don’t Skip Dealer Finance in Your Comparison
- Dealer promotional finance can genuinely beat bank and broker rates. Rates as low as 4.99% to 7.99% show up regularly on new bikes through manufacturer finance deals.
- These promotions are usually tied to specific models or timeframes. So they’re worth checking even if you assumed a bank loan would automatically be cheaper.
- Comparing all three options takes the same time as comparing two. Bank, broker, and dealer finance side by side gives you the full picture before you sign anything.
- Fees still apply beyond the headline rate. Application fees, ongoing account fees, and early repayment fees can all affect the real cost, so check these alongside the rate itself.
For related reading, see our guides to Low Doc Home Loans: What You Actually Need and What It Costs and UBank Interest Rates: The Intro Rate vs the Rate You’ll Actually Keep.
FAQ: Motorbike Loans
What’s the average interest rate on a motorbike loan in Australia?
Around 9.38% for secured loans and 10.32% for unsecured loans on average, though your personal rate depends heavily on your credit score.
Is a secured or unsecured motorbike loan better?
Secured loans are usually cheaper, about 1% lower on average, but the bike can be repossessed if you default. Unsecured loans cost more but offer more flexibility.
Does my credit score affect my motorbike loan rate?
Yes, significantly. A score above 700 typically gets rates from 5.67% to 8%, while scores between 500 and 700 usually mean 9% to 14% instead.
Can I get a loan for an older motorbike?
Standard secured financing usually isn’t available for bikes older than 7 years. Unsecured finance or specialist dealer finance are the more realistic options in that case.
What loan term gets the best rate on a motorbike loan?
A 4-5 year term is generally considered the pricing sweet spot, balancing manageable monthly repayments against the total interest paid over the life of the loan.
You may also like
 Line of Credit: The Three Types Explained in One Place
 Bad Credit Car Loans Australia: The Real Rate Range and What Actually Helps
 Caravan Finance: The Realistic Rate Range, Not Just the Best Case
 Dealer Administration Fees on Used Cars: What’s Legal, What’s Not (2026)
 Bad Credit Loans in Canada: The Real Rates You’ll Pay
 Game Score Calculator – Basketball Performance Indicator
Related posts:
Line of Credit: The Three Types Explained in One Place
Bad Credit Car Loans Australia: The Real Rate Range and What Actually Helps
Caravan Finance: The Realistic Rate Range, Not Just the Best Case
Dealer Administration Fees on Used Cars: What’s Legal, What’s Not (2026)
Bad Credit Loans in Canada: The Real Rates You’ll Pay