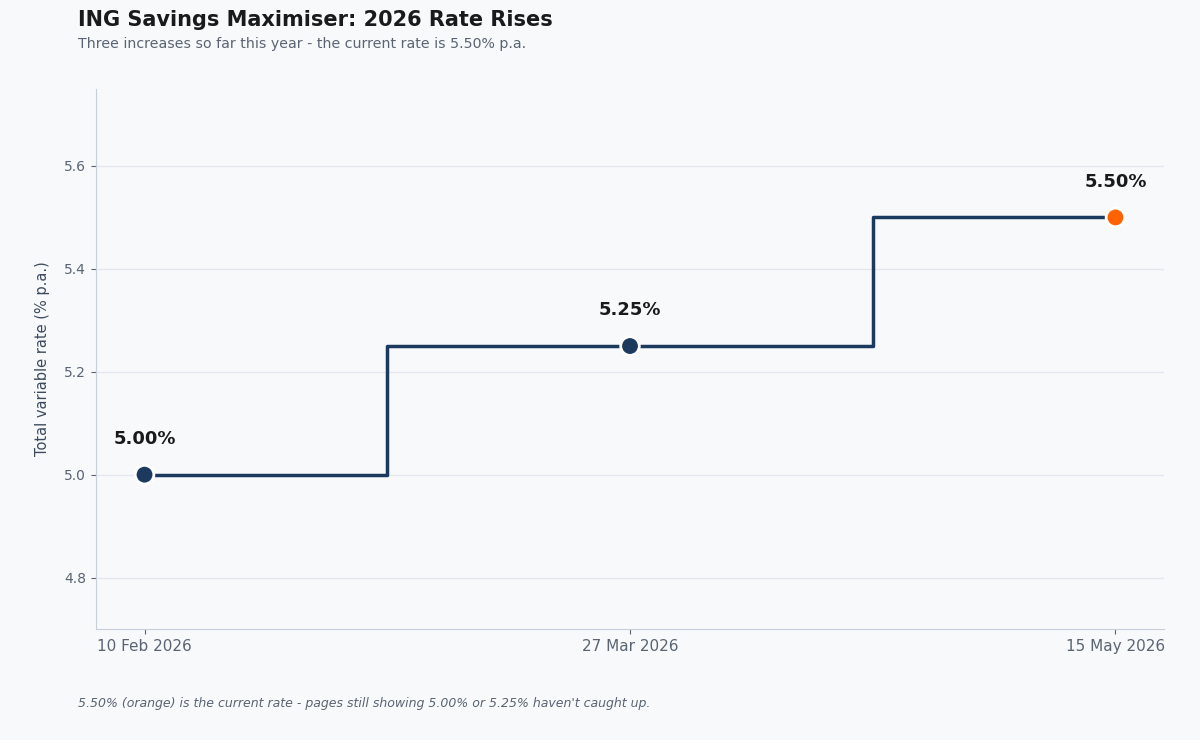

Search for the ING Savings Maximiser rate right now and you’ll find at least three different numbers. Here’s which one is actually current, why the others are stale, and exactly what you need to do each month to earn it.
This bank is one of 19 compared in our Australia Term Deposit Rates comparison guide.
Quick Answer: ING Savings Maximiser
The ING Savings Maximiser pays a total variable rate of 5.50% per annum when you meet the monthly bonus conditions, on balances up to $100,000. This rate took effect on 15 May 2026, per ING’s own announcement. Some pages still show 5.25% or an older figure. Those are simply behind the latest rate rise. Without meeting the conditions, you earn a base rate of just 0.01% per annum that month.
Why Different Sites Show Different Rates
- ING raised the rate three times so far in 2026. It moved from 5.00% (10 February) to 5.25% (27 March) to 5.50% (15 May), each time confirmed directly by ING’s own newsroom.
- Some review sites simply haven’t caught up. A page last checked in March will still show 5.25%, even if the byline claims to be current.
- One popular review site even lists the wrong base rate. It quotes roughly 0.55% as the base rate, when ING’s own product page states 0.01% per annum for balances that miss the monthly conditions.
- Always check the date behind the number, not just the number itself. A rate this many months into a rise cycle is easy to misquote on an unrefreshed page.
The Three Monthly Conditions, Plainly Stated
- Deposit at least $1,000 from an outside source. This has to land in an eligible ING account, such as your Savings Maximiser or linked Orange Everyday account, from somewhere outside ING.
- Make 5 or more settled card purchases. These need to be genuine, completed transactions, not pending ones, on an eligible ING card.
- Grow your nominated Savings Maximiser balance. Your balance needs to be higher at month’s end than at the start, not counting the interest you earned.
- Meet all three in the same calendar month. The bonus rate then applies the following month, not the same month you met the conditions.
What Happens If You Miss a Condition
- You’re not locked out or penalised. Missing a condition simply means you earn the 0.01% base rate on your balance for that particular month.
- The bonus resets automatically the next month. There’s no waiting period or reapplication. Meet all three conditions again, and the 5.50% rate applies the month after.
- This makes the account forgiving for irregular savers. A quiet month where you don’t deposit or spend just costs you that month’s bonus, not the account itself.
- Set a simple monthly habit to avoid missing it. A recurring transfer plus your everyday card spending usually covers all three conditions without extra effort.
What the Rate Actually Earns You
- On a $10,000 balance, the difference is significant. At 5.50% for a full year, that’s roughly $550. At the 0.01% base rate, it’s about a dollar.
- The bonus only applies up to $100,000. Any balance above that earns the lower base rate on the excess, so very large balances see a blended return.
- It’s a variable rate, so it can change again. ING has moved this rate several times in 2026 already, mostly following official cash rate movements.
- Compare it against your linked Orange Everyday account too. The Maximiser is built for savings growth, not everyday spending, so keep the two accounts working together.
For related reading, see our guides to ME Bank Term Deposit Rates: The Real Table (One Comparison Site Shows None) and Line of Credit: The Three Types Explained in One Place.
FAQ: ING Savings Maximiser
What is the current ING Savings Maximiser interest rate?
5.50% per annum total variable rate, effective from 15 May 2026, when you meet the monthly conditions.
Why do some websites show a lower rate?
They haven’t been updated since ING’s most recent rate rise. The rate moved from 5.00% to 5.25% to 5.50% across three increases in 2026.
What are the monthly bonus conditions?
Deposit $1,000 from an outside source, make 5+ settled card purchases, and grow your balance, all within the same calendar month.
What if I miss a condition one month?
You simply earn the 0.01% base rate for that month. There’s no penalty, and the bonus rate resumes the next month you meet all three conditions.
Is there a limit on how much earns the bonus rate?
Yes. The bonus rate applies to balances up to $100,000. Anything above that earns the lower base rate.
You may also like
 ING Term Deposit Rates: Why “ING Direct” Is an Outdated Name
 UBank Interest Rates: The Intro Rate vs the Rate You’ll Actually Keep
 Australia Term Deposit Rates 2026: Every Major Bank Compared
 Kids Savings Account Interest Rates: The Current Top Picks (August 2026)
 Bankwest Savings Interest Rates: Easy Saver vs Hero Saver Explained
 SMSF Term Deposit Rates: What Comparison Sites Miss (2026)
Related posts:
ING Term Deposit Rates: Why “ING Direct” Is an Outdated Name
UBank Interest Rates: The Intro Rate vs the Rate You’ll Actually Keep
Australia Term Deposit Rates 2026: Every Major Bank Compared
Kids Savings Account Interest Rates: The Current Top Picks (August 2026)
Bankwest Savings Interest Rates: Easy Saver vs Hero Saver Explained
[…] For related reading, see our guides to ME Bank Term Deposit Rates: The Real Table (One Comparison Site Shows None) and ING Savings Maximiser: The Real Current Rate and Why Sites Disagree. […]