
Most guides explain how to open a joint bank account and stop there. The real questions people search for usually come from a specific situation: a breakup, a death, or a dispute over who gets what. Here’s what most pages skip.
Quick Answer: Joint Bank Account
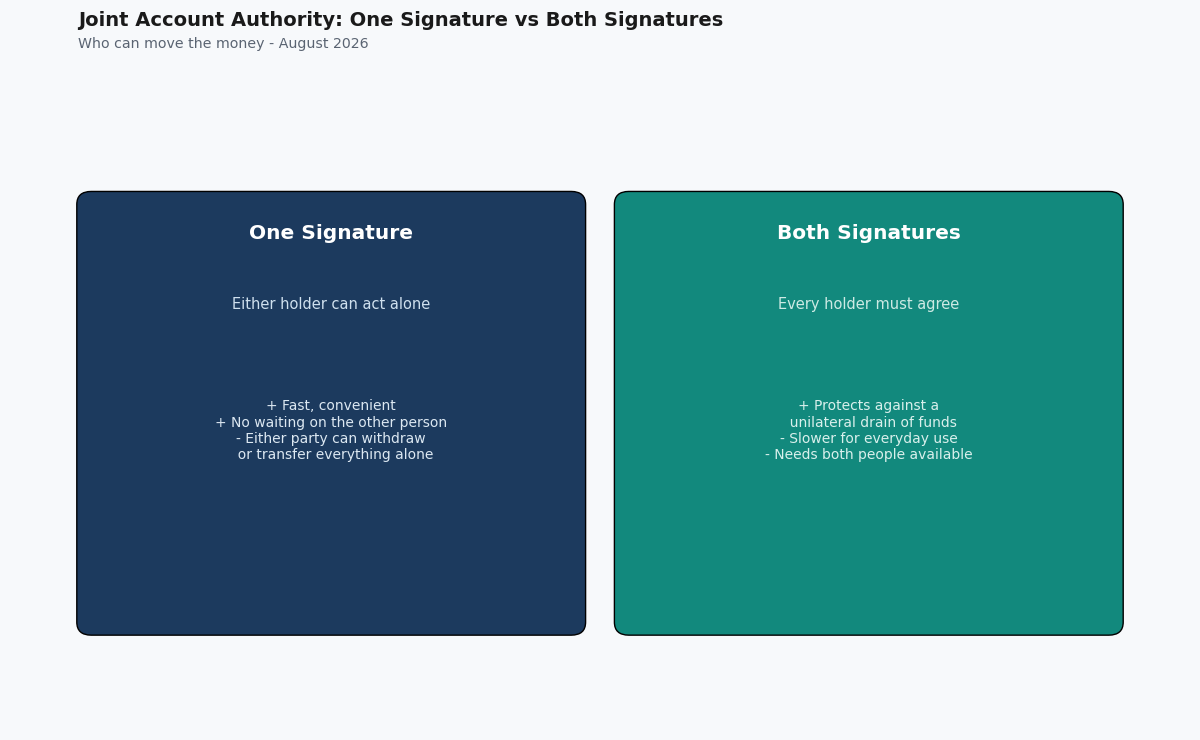
A joint bank account is one that more than one person can access, set up as either “one signature” (anyone can withdraw alone) or “both signatures” (everyone must agree). So, you share liability for debts on the account, meaning another holder’s overspending can affect your own credit report. If a joint account holder dies, the funds generally pass automatically to the surviving holder, outside the deceased’s will, though banks can have their own process for this. Closing a joint account after a dispute requires all holders’ agreement, or in some cases, a court order.
The Two Authority Types, and Why This Matters
- “One signature” accounts let any holder act alone. One person can withdraw, transfer, or spend the full balance. No need to tell the other holder first.
- “Both signatures” accounts need everyone’s agreement. No withdrawal happens unless every holder signs off. It’s slower, but far safer against one person draining the funds.
- Most everyday joint accounts default to one signature. If you haven’t asked for a both-signatures setup, assume either person can move the money alone.
- This choice matters most in high-conflict situations. A both-signatures account protects you if you’re worried about a partner acting without your knowledge. A one-signature account trades that protection for convenience.
Shared Debt Liability: The Risk Most People Miss
- You’re liable for debts on the account, not just your own spending. If your co-holder runs up an overdraft, you can be held responsible for the full amount. Not just your share.
- This can affect your personal credit report. A joint account debt showing as unpaid can damage your own credit history. Even if you didn’t cause the debt yourself.
- This liability exists no matter who spent the money. The bank generally doesn’t care who’s “at fault” internally. Both names on the account means both people are on the hook.
- Think about this before adding someone to an existing account. Adding a joint holder means their financial behaviour becomes partly your risk too.
What Happens If a Joint Account Holder Dies
- Funds generally pass to the surviving holder automatically. Most Australian joint accounts work on a right of survivorship. The balance usually doesn’t get tied up in the deceased’s estate or will.
- This differs from how a sole account gets treated. A sole account is usually frozen on death until probate is granted. A joint account often stays accessible to the surviving holder much sooner.
- Banks still run their own verification process. You’ll typically need a death certificate and to follow your bank’s steps. Even though the funds aren’t part of the deceased’s estate.
- Confirm this with your specific bank, since policies vary. Not every bank or account type handles this the same way. Check your bank’s own terms rather than assuming.
Closing a Joint Account During a Dispute
- All holders generally need to agree to close the account. If you’re on good terms, this is straightforward. Clear any overdraft, split the remaining funds, and get written confirmation from the bank.
- A dispute makes this genuinely harder. If one party won’t cooperate, the bank typically won’t act on your instruction alone. Both names are legally tied to the account.
- Some banks can freeze a disputed account temporarily. Contact your bank and explain the dispute. They may place a hold while things get sorted, stopping one party from draining it further.
- Legal advice may be needed for a genuine standoff. If agreement isn’t possible, a family lawyer or a small claims process may be needed to work out how funds get split.
For related reading, see our guides to Open Bank Account Online Australia: The Real Timeline and Low Doc Home Loans: What You Actually Need and What It Costs.
FAQ: Joint Bank Account
How does a joint bank account work?
More than one person can access it. It’s set up as either “one signature” (anyone can withdraw alone) or “both signatures” (everyone must agree), and holders share liability for debts.
Am I liable for my joint account holder’s debts?
Yes, generally for the full debt connected to the account, not just your share, and this can affect your own credit report.
What happens to a joint account when someone dies?
Funds typically pass automatically to the surviving holder under right of survivorship, generally outside the deceased’s estate, though you’ll need to follow your bank’s verification process.
Can I close a joint account if the other person disagrees?
Not unilaterally in most cases. Banks generally need all holders’ agreement, though they may freeze a disputed account temporarily while things get resolved.
Can one person empty a joint account without permission?
Yes, if it’s a “one signature” account. Either holder can typically withdraw or transfer funds without the other’s knowledge under this setup.
You may also like
 Open Bank Account Online Australia: The Real Timeline
 Judo Bank Term Deposit Rates: The Full Table and Why It’s Shaped This Way
 How to Write a Cheque in Australia (Before They’re Phased Out in 2029)
 Greater Bank Term Deposit Rates: The Tier Trap Nobody Warns You About
 Debit Card Daily Withdrawal Limit: What Each Australian Bank Actually Allows
 Macquarie Bank Term Deposit Rates: Two Products, Two Different Tables
Related posts:
Open Bank Account Online Australia: The Real Timeline
Judo Bank Term Deposit Rates: The Full Table and Why It’s Shaped This Way
How to Write a Cheque in Australia (Before They’re Phased Out in 2029)
 How to Read a Cheque in Canada: Every Field Explained
Macquarie Bank Term Deposit Rates: Two Products, Two Different Tables